


After a Wildfire Total Loss: A Steady Path Through the Claim
Losing a home to wildfire turns into a long paperwork project. This guide walks through contents, living expenses, debris removal and the rebuild-or-relocate decision.
Read the guide
When the insurer accepts the claim but the payment won’t rebuild the roof, the stucco or the house, New Mexico Insurance Appraiser builds an independent, line-by-line valuation and takes it through the appraisal clause in your policy.
Most short claims aren’t denials. They’re missing parapet flashing, a stucco wall priced as a patch, a roof measured two squares small or a cooler nobody looked at. New Mexico Insurance Appraiser exists for the gap between what the insurer agreed to cover and what the repair actually costs.
As a New Mexico Insurance Appraiser, we work for the policyholder inside the appraisal process. We don’t argue coverage and we don’t inflate numbers — we document the loss well enough that the panel can see it.
Twelve services, one goal: a valuation of your loss that holds up. Start with an estimate review, or bring us in once appraisal has been demanded.
 01
We serve as the appraiser you name when your policy’s appraisal clause is invoked on a disputed claim.
Learn more 02
Independent valuation for disputed homeowners claims on stucco, adobe, frame and manufactured homes.
Learn more 03
Appraisal for commercial buildings, apartment complexes and HOA or condo associations across New Mexico.
Learn more 04
Hail claims on shingle and tile roofs, swamp coolers, skylights and stucco, valued independently.
Learn more 05
Valuation for spring wind, monsoon microburst and eastern-plains tornado damage to homes and buildings.
Learn more 06
Plumbing leaks and monsoon roof leaks through parapets and canales, valued room by room.
Learn more 07
Independent valuation for house fires, structure fires and smoke or soot damage throughout a building.
Learn more 08
Total and partial wildfire losses: rebuild cost, smoke and ash, contents, debris removal and living expense.
Learn more 09
Pueblo Revival and Territorial flat roofs, parapets, canales and stucco matching, valued by specialists.
Learn moreHail on the Llano Estacado, wildfire in the Sacramento Mountains, freezes in Los Alamos and monsoon microbursts in Las Cruces. A New Mexico Insurance Appraiser has to know how each region’s weather shows up on a building — and in an estimate.
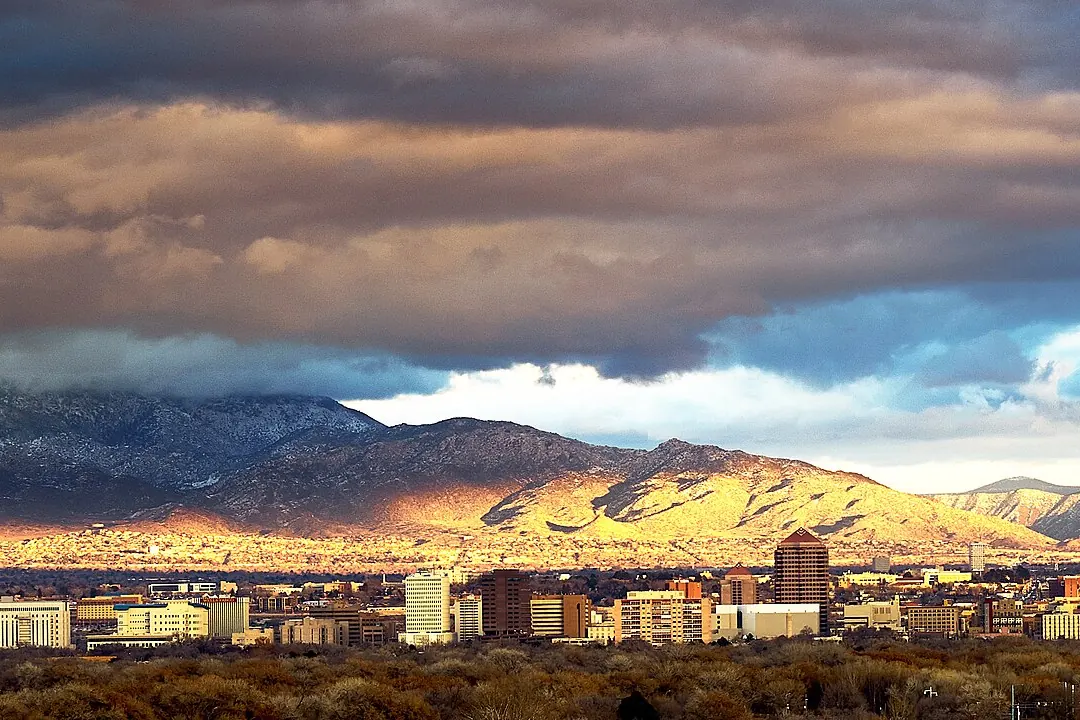
The state’s largest housing market. Stucco ranch homes in the Northeast Heights, flat-roofed Pueblo Revival houses near the river and pitched-roof subdivisions on the West Mesa all take hail differently.
Albuquerque · Rio Rancho · Los Lunas
Elevation changes everything: adobe and historic-district rules in Santa Fe, wildfire exposure in the Jemez and Sangre de Cristo foothills, and hard freezes that split pipes.
Santa Fe · Los Alamos · Farmington · Taos
Open country where spring and summer storms can drop very large hail and spin up tornadoes. Oilfield growth adds commercial yards, apartments and new subdivisions to the claim mix.
Clovis · Roswell · Hobbs · Carlsbad
Desert wind and monsoon downbursts around Las Cruces and the Tularosa Basin, and fire-then-flood risk in the forested mountains above Ruidoso.
Las Cruces · Alamogordo · RuidosoThe appraisal clause turns an open-ended argument into a defined process. Here is how New Mexico Insurance Appraiser moves a file through it.
We read the policy, the insurer’s estimate and your photos, then tell you honestly whether appraisal fits.
Our own site visit, measurements and photos — never an edited copy of the carrier’s scope.
A line-item estimate priced for your part of New Mexico, with code items and overhead handled the way your policy reads.
We sit down with the insurer’s appraiser line by line. Many differences close at this stage.
Anything left goes to the umpire. Two signatures set the amount of loss.
Put in the two numbers you already have. A large difference is worth a conversation with a New Mexico Insurance Appraiser; a small one may close faster with a documented supplement.
The full claim gap net-recovery estimator adds appraiser and umpire fees so you see a realistic net figure. Example numbers are illustrative.
Check the insurer’s math before you call anyone. Every tool runs in your browser; nothing is stored or sent.
 ΔEstimator
Measure the dispute, test where an award might land and subtract appraiser and umpire fees to see the net.
Open ½Calculator
Split a replacement-cost claim into the first ACV check and the depreciation held back until repairs.
Open ◿Converter
Turn a footprint and pitch into true roof squares, order quantity and a steep-charge check.
Open %Converter
See a 1–10% wind/hail deductible in dollars and what a storm claim would actually pay.
Open ▦Planner
Build a date-of-loss timeline for notice, repairs, proof of loss, holdback and suit dates, then export .ics.
Open✓ChecklistTwelve yes/no questions that score your claim file and build a to-do list before you demand appraisal.
Open ▤Estimator
Rough out a room-by-room personal property inventory and compare it with your Coverage C limit.
OpenWe work in every New Mexico county. These local pages cover the places our claims come from most.
Each solves a different problem. New Mexico Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.
Straight answers about how appraisal works, what it costs and when it’s the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree about the cost. As your appointed appraiser we inspect, build an independent line-item estimate, work with the insurer’s appraiser and, if needed, present unresolved items to an umpire.
No. A public adjuster handles the whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage has been accepted, you have the insurer’s itemized estimate, and the gap to a contractor’s number is meaningful — often more than about ten percent or several thousand dollars.
On the amount of loss, generally yes once two of the three panel members sign. Coverage questions are separate and may need a New Mexico attorney.
Each side usually pays its own appraiser and splits the umpire. Our fee is put in writing before any work starts, and the first conversation is free.
Yes. We work statewide in all 33 counties, including Las Cruces, Santa Fe, the eastern plains, the Four Corners and the mountain communities.
Practical reading on wildfire claims, hail on flat roofs, monsoon leaks and how to invoke appraisal.
Losing a home to wildfire turns into a long paperwork project. This guide walks through contents, living expenses, debris removal and the rebuild-or-relocate decision.
Read the guideFlat roofs with parapets, coatings and rooftop coolers hide hail damage well. Here’s how to document it so it doesn’t get called cosmetic.
Read the guideInvoking appraisal is mostly about reading your policy closely and putting a clear demand in writing. Here’s how to do both and pick the right appraiser.
Read the guideTell us what happened and what the insurer offered. We’ll review it and tell you whether appraisal is worth pursuing — no pressure and no obligation.
